Buying a boat is exciting, but the monthly payment shown by a dealer or lender is only one part of the financial picture. A comprehensive payment calculator for boats can help you estimate the amount financed, monthly payment, total interest, and the effect of sales tax, fees, down payment, and loan term before you make a borrowing decision.
Whether you’re exploring luxury yachts or modest fishing vessels, calculating boat payments correctly is the first step to ensuring your dream doesn’t become a financial anchor. Use our advanced calculator below to run your numbers.
How a Boat Payment Calculator Works
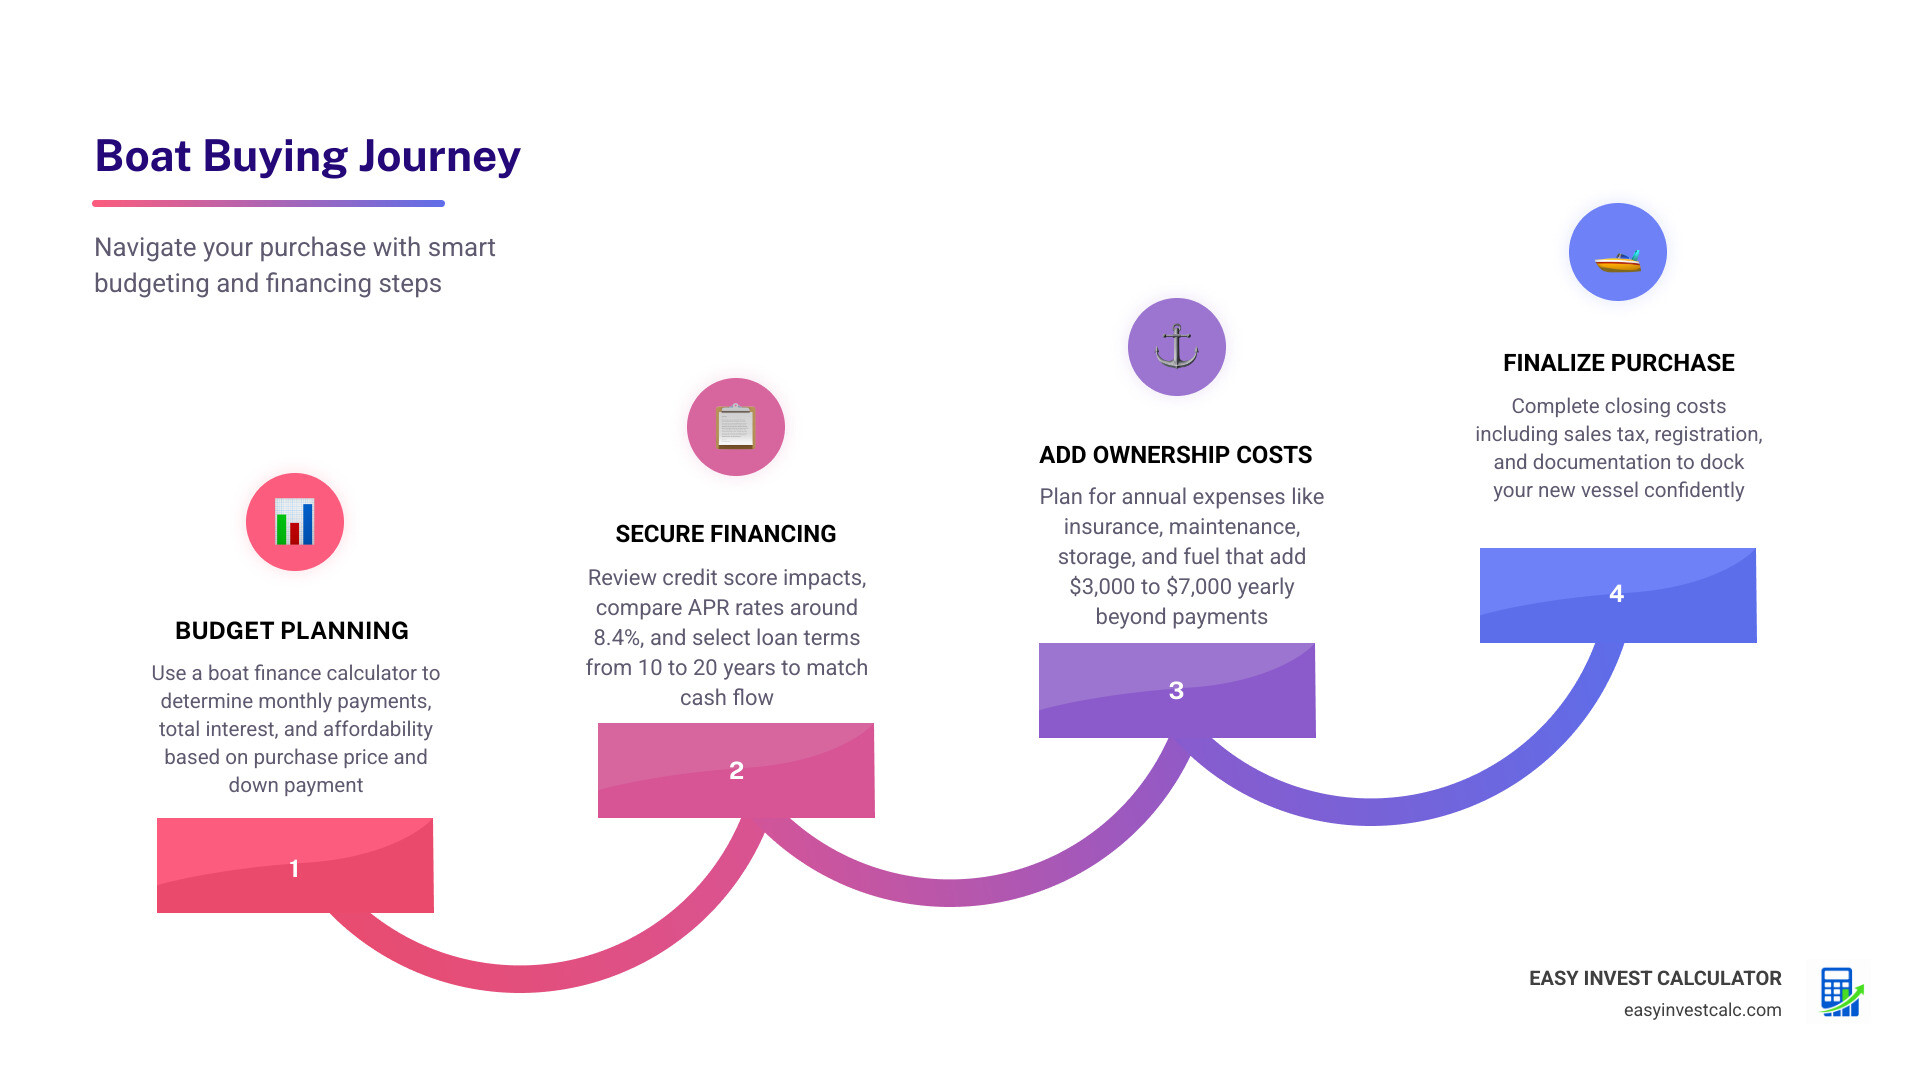
At its core, a boat calculator payment tool takes the complexity out of amortization. When you borrow money for a boat, you aren’t just paying back the price of the vessel; you are paying for the privilege of using the bank’s money. First, the calculator estimates the amount financed (boat price + sales tax + fees – down payment). It then applies the quoted APR across the selected number of monthly payments.
If you have ever used an EMI Calculator, you know the drill. However, a marine-specific calculation requires more nuance. Because boat loans often have much longer terms than car loans—sometimes stretching up to 20 years—the way interest compounds can be eye-opening.
Why Your Boat Loan Down Payment Changes Everything
Most boat buyers focus entirely on the sticker price. That’s the wrong place to start. Using a boat loan calculator down payment feature is the fastest way to see exactly how much you’ll owe each month — and how much your upfront cash saves you over time.
Your down payment is the single biggest lever you control before you ever sign a loan agreement. Put down more, and your monthly boat payment drops, your interest costs shrink, and your risk of going “underwater” on the loan decreases — because boats depreciate fast.
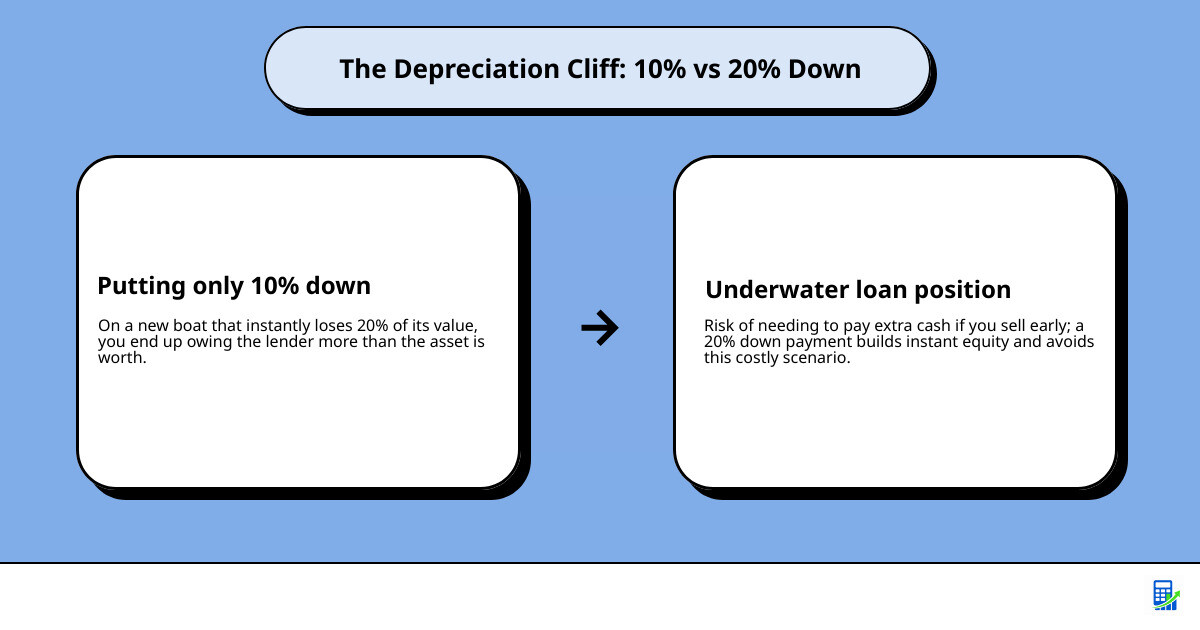
New boats can lose 20% of their value the moment they hit the water. If you only put 10% down, you are instantly “underwater” on the loan. A 20% down payment acts as a financial life jacket. It ensures you have immediate equity.
Boat financing example how much downpayment do you need?
If you are looking for a clear boat financing example how much downpayment impacts your wallet, look at this breakdown for an $80,000 boat (assuming a 7% APR over 10 years):
| Down Payment | Boat Price | Loan Amount | Est. Monthly Payment (7% APR, 10 yr) |
|---|---|---|---|
| 10% ($8,000) | $80,000 | $72,000 | ~$837 |
| 15% ($12,000) | $80,000 | $68,000 | ~$790 |
| 20% ($16,000) | $80,000 | $64,000 | ~$743 |
| 25% ($20,000) | $80,000 | $60,000 | ~$697 |
Estimates based on industry rate data. Your actual rate will vary by credit score and lender. Using a loan calculator boat with down payment allows you to replicate this exact math for your personal budget.
The Impact of Credit Scores and Loan Terms
Your credit score is the captain of your financial ship. It determines whether you get a “premier” interest rate or a “subprime” one that makes your boat loan payments twice as expensive over time.
Data from recent years shows a clear divide in how much borrowers pay based on their FICO scores. Even a 1% difference in APR can change your financial life. Someone with “Fair” credit can pay thousands more in interest than someone with “Excellent” credit for the exact same boat.
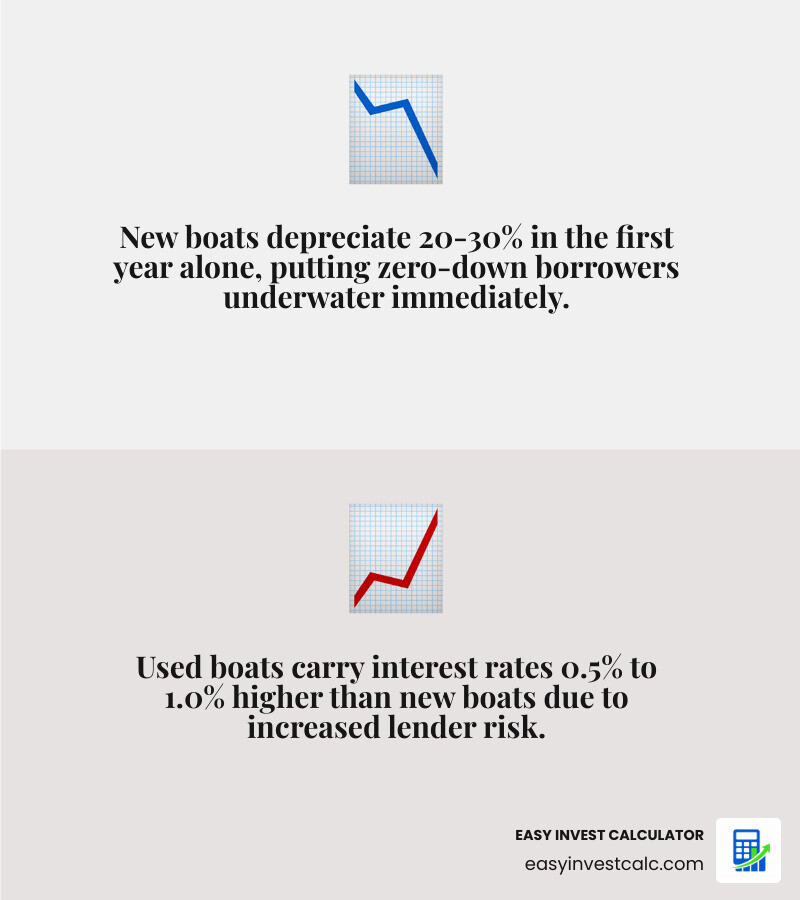
Navigating boat loan terms and durations
The length of your loan is a double-edged sword when securing your boat loan payment.
- Short-term loans (5–10 years): These have higher monthly payments but significantly lower total interest costs. You build equity in the boat much faster.
- Long-term loans (15–20 years): These make expensive boats “affordable” by dropping the monthly payment. However, you will pay a mountain of interest. On a 20-year loan, you might end up paying for the boat twice over.

Before committing to a long term, check your State boat registration and tax info to see if there are additional annual fees that might make a high monthly payment even harder to manage.
Hidden Costs: What Your Boat Loan Calculator Doesn’t Show
If you only budget for the number you see on a calculator, you’re going to get “soaked.” The monthly boat payment is just the “entry fee” to boating. Industry experts suggest that annual ownership costs for a boat can range from 10% to 20% of the boat’s value.

- Marine Insurance: Expect to pay 1.5% to 3% of the boat’s value annually.
- Maintenance: Regular oil changes, hull cleaning, and winterization are non-negotiable.
- Storage and Dockage: Depending on your location, a marina slip can cost hundreds or even thousands per month.
- Upfront Fees: Loan origination fees, marine surveys (for used boats), and documentation fees can add up quickly. Check the Federal maritime documentation guide if buying a larger vessel.
If these numbers look scary, it might be time to look into the Debt Counseling Process: How to Prepare for Debt to ensure your total household budget can handle the expenses a boat represents.
Secured vs Unsecured Boat Loans
| Feature | Secured Boat Loan | Unsecured Personal Loan |
|---|---|---|
| Collateral | The boat itself | None |
| Typical APR | Lower (e.g., 6.5% – 9%) | Higher (e.g., 10% – 18%) |
| Loan Terms | Up to 20 years | Usually 5-7 years |
| Risk | Repossession if you default | Lawsuit/Credit damage |
Secured loans are the standard for most significant boat purchases because lenders can seize the boat if you stop paying, allowing them to offer much lower interest rates and longer durations.
Pro Tips to Save on Your Marine Financing
We want you to enjoy the water, not worry about the bank. Here are three professional strategies to keep your costs down:
- The “20% Rule”: As discussed, a healthy boat loan down payment reduces your loan-to-value ratio, often triggering a lower interest rate.
- Bi-Weekly Payments: Instead of one monthly payment, pay half the amount every two weeks. This results in 13 full payments a year, shaving years off your loan.
- Accelerate Your Payoff: Making principal-only payments is the fastest way to debt freedom. Learn more about this in Extra Payments: The Secret Sauce for Debt Freedom.

You can visualize these savings by using an Amortization Schedule with Extra Payments. Seeing the “Total Interest” number drop as you add extra principal payments is incredibly satisfying.
Frequently Asked Questions
What is the typical down payment for a boat?
The typical range is 10% to 30%. While “zero-down” loans exist for borrowers with pristine credit, they are rare and usually come with higher interest rates. Lenders prefer you to have “skin in the game.”
Is boat loan interest tax deductible?
Potentially, yes. Under IRS rules, a boat can be considered a “qualified residence” if it has basic living facilities (sleeping, cooking, and toilet). Check the IRS Publication 936 or IRS Second Home Deduction Eligibility guidelines, and always consult a tax professional.
How long can you finance a boat?
While 10 years (120 months) is the standard for mid-sized boats, many lenders offer 15 or 20-year terms for loans exceeding $75,000 to $100,000. Keep in mind that longer terms result in much higher total interest costs.
Can I get a boat loan with a 600 credit score?
Yes, but it will be expensive. A 600 score falls into the “subprime” category. You should expect an APR significantly higher than average (potentially 12% to 18%), and you will likely be required to provide a larger down payment (25%+).
Are boat loan interest rates fixed or variable?
Most boat loans are fixed-rate, meaning your monthly payment stays exactly the same for the entire term. Variable-rate loans exist and often start with a lower rate, but they can increase if market interest rates rise.
Can I finance boat sales tax?
Sometimes. Some lenders may permit certain taxes or fees to be included in the financed amount, while others may require them to be paid separately out of pocket. Confirm the treatment with your lender.
Are boat loan interest rates higher than car loans?
Usually, yes. Boats are considered luxury or recreational items, not necessities like cars. Therefore, lenders perceive them as slightly higher risk, which is reflected in slightly higher interest rates compared to standard auto loans.
Conclusion
Buying a boat should be about freedom, not financial stress. By using a boat payment calculator, you can strip away the guesswork and see exactly how your upfront investment protects your future. Understand the difference between Good Debt vs Bad Debt, plan for the hidden costs of ownership, and enjoy your time on the water!
Disclaimer: This article and calculator are for educational and planning purposes only. They are not a loan offer or financial recommendation. Consult with your lender or a financial professional for personalized advice. (Source: CFPB)
Founder of EasyInvestCalc.com with 8+ years of experience in personal finance. Sunita simplifies complex financial mathematics—from SIP compounding to tax planning—empowering Indian investors to make smart, debt-free decisions based on real market mechanics.