Bike EMI Calculator – Calculate Two-Wheeler Loan EMI & Interest
A bike EMI calculator helps you estimate your monthly two-wheeler loan EMI, total interest and total repayment before choosing a bike loan. Enter your loan amount, interest rate and repayment tenure to understand what your monthly payment could look like.
You can also compare different down payment amounts and loan tenures to see how they affect your EMI and total interest. This can help you choose a loan amount that fits your budget before visiting a showroom or applying with a lender.
Bike EMI Calculator
Calculate your two-wheeler loan EMI, total interest and repayment amount.
Bike EMI Formula
EMI = P × r × (1 + r)n ÷ ((1 + r)n − 1)
P = Loan amount, r = monthly interest rate, n = number of monthly instalments.Quick Answer: How to Calculate Your Bike EMI
| Input | What to Enter |
|---|---|
| Loan Amount | On-road price minus your down payment |
| Interest Rate | The annual interest rate offered by your lender |
| Tenure | Number of months you will take to repay the loan |
| Result | Estimated monthly EMI, total interest and repayment |
Use the Bike EMI Calculator above to compare different loan amounts, interest rates, tenures and down payments before making a borrowing decision.
The formula behind a standard reducing-balance EMI calculation is:
EMI = P × r × (1+r)n ÷ [(1+r)n − 1]
- P = Principal loan amount
- r = Monthly interest rate (annual rate ÷ 12 ÷ 100)
- n = Loan tenure in months
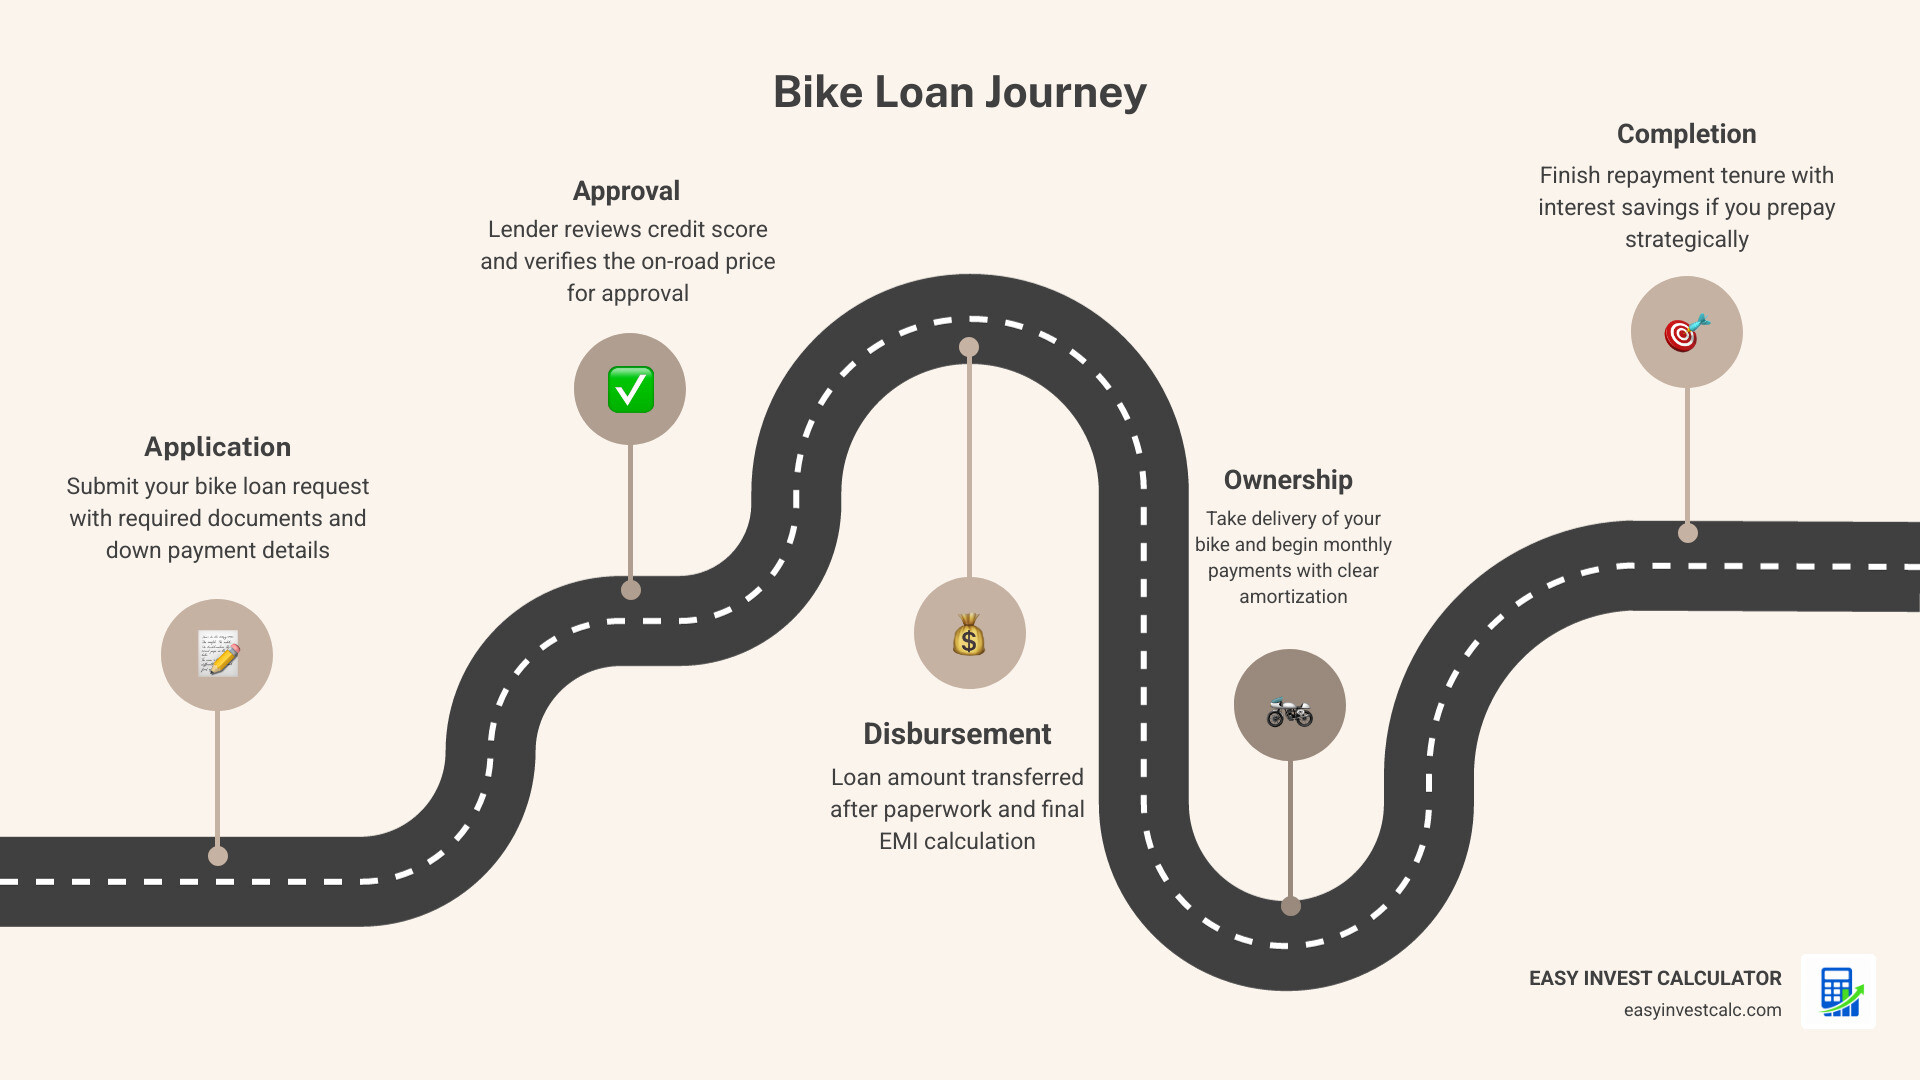
Buying a bike is exciting, but understanding the monthly payment and total cost of the loan is just as important. A bike loan does not cost only the amount borrowed because interest and applicable loan charges can increase the overall amount you repay.
For example, a ₹1 lakh loan at 15% annual interest for 48 months has an estimated EMI of about ₹2,783 per month. The total repayment would be about ₹1.34 lakh, before considering any separate fees or charges.
That is why a bike EMI calculator is useful before you commit to a loan. Instead of looking only at the monthly EMI, you can compare the total interest and total repayment for different loan scenarios.
This guide explains how a bike loan calculator works, how a down payment changes your EMI, how interest and tenure affect the total cost, and how to compare different financing scenarios.
Bike EMI Calculator With Down Payment
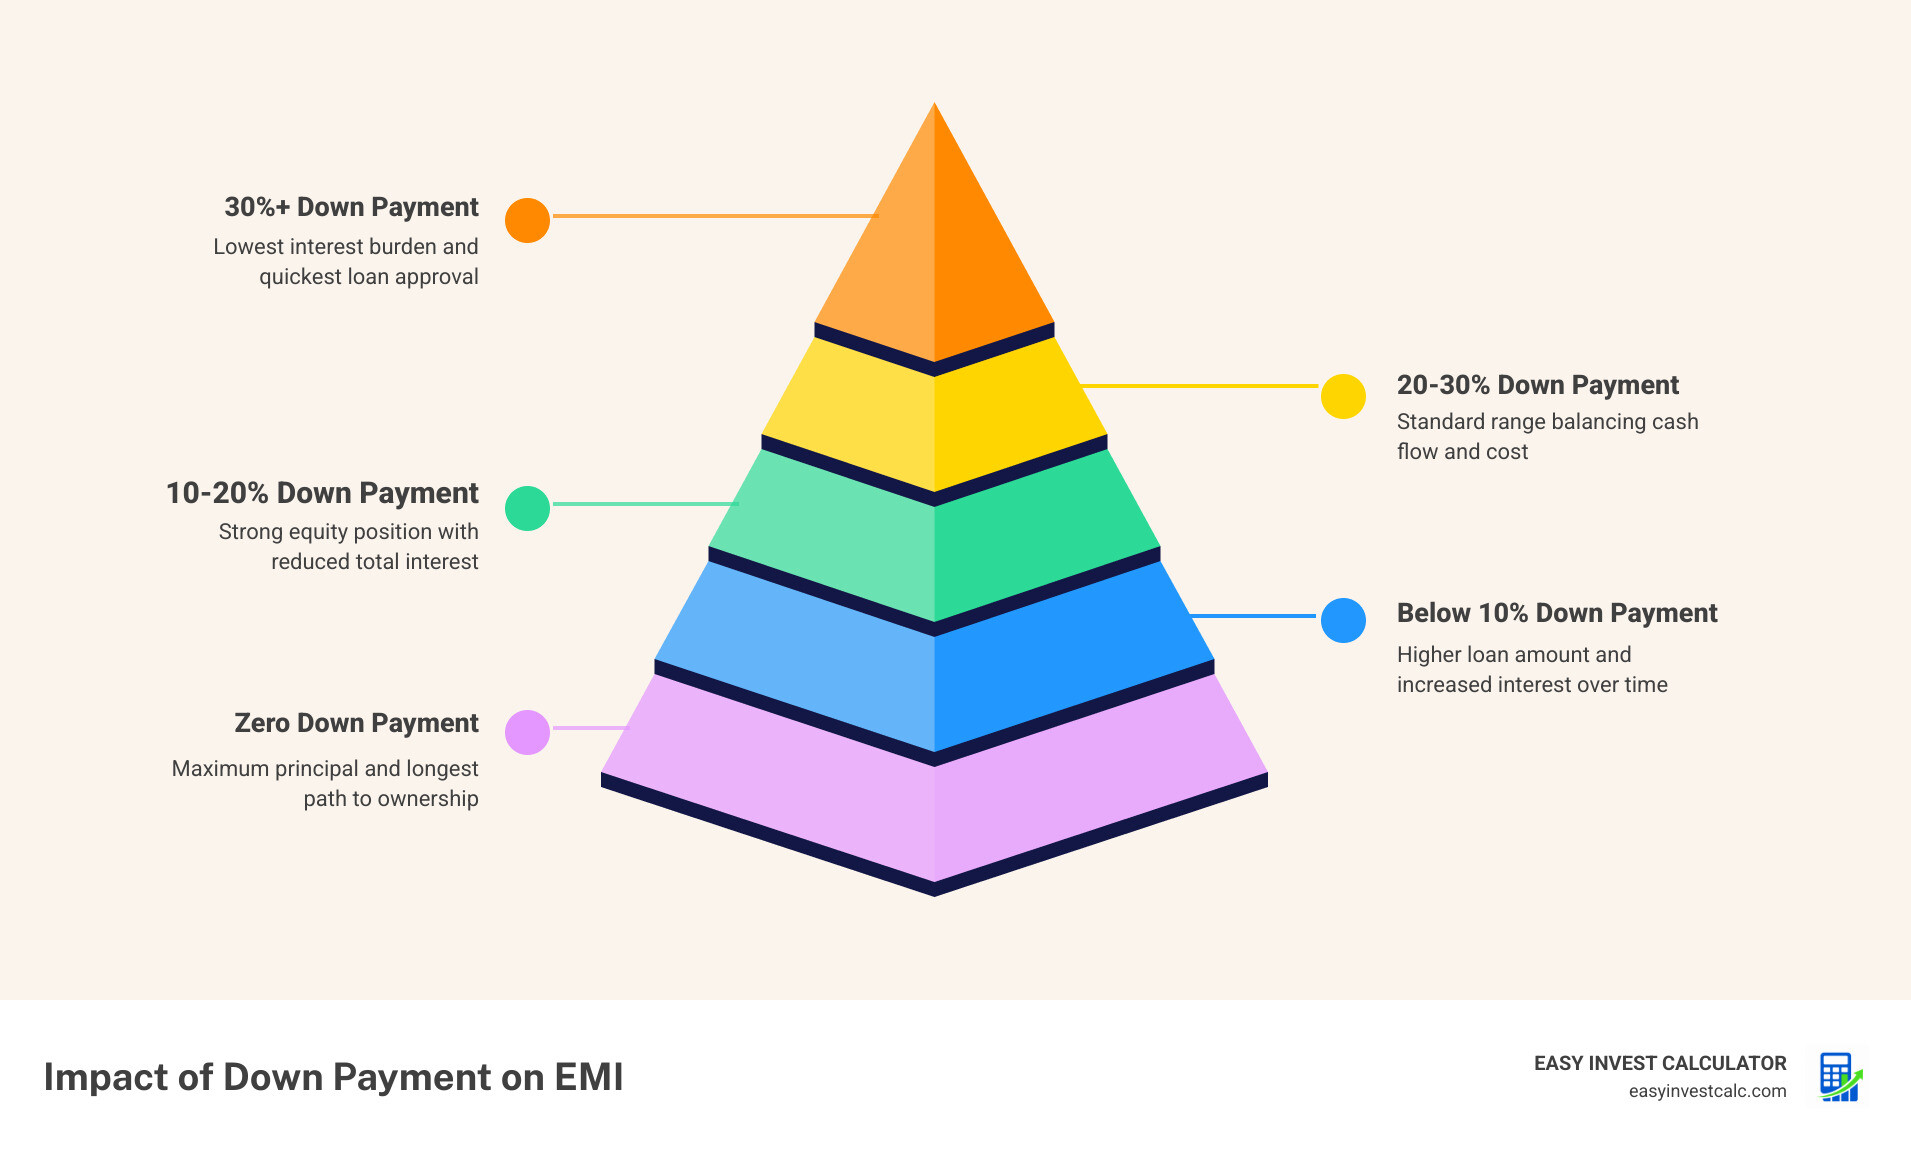
A bike EMI calculator with down payment helps you see how paying more upfront can reduce the amount you need to borrow. A smaller loan principal generally means a lower EMI and less interest over the same repayment period, assuming the interest rate and tenure remain unchanged.
| On-Road Price | Down Payment | Loan Amount | Interest Rate | Tenure | Estimated EMI |
|---|---|---|---|---|---|
| ₹1,50,000 | ₹30,000 | ₹1,20,000 | 12% p.a. | 36 months | ₹3,986 approx. |
In this example, the estimated EMI is about ₹3,986 per month. The total repayment over 36 months would be approximately ₹1,43,486, including about ₹23,486 in interest, before any separate lender fees.
Try different down payment amounts in the calculator above to compare how borrowing ₹1,20,000, ₹1,10,000 or another amount could change your monthly payment.
Bike EMI Calculator Terms Simplified
Understanding the Bike EMI Calculator and How It Works
At its core, a bike EMI calculator converts three important loan inputs—principal, interest rate and tenure—into an estimated monthly payment. Understanding these inputs makes it easier to compare loan offers instead of focusing only on the EMI shown by a lender or dealership.
The Four Pillars of EMI
- Loan Principal (P): This is the amount you actually borrow. If the financed amount is based on the on-road price, the amount borrowed may be the on-road price minus your down payment, subject to the lender’s terms.
- Monthly Interest (r): Lenders generally quote an annual interest rate. For the standard EMI formula, the annual rate is converted into a monthly rate by dividing it by 12 and then by 100.
- Repayment Tenure (n): This is the number of months over which the loan is repaid. Common examples include 12, 24, 36, 48 and 60 months, depending on the lender.
- Reducing Balance Method: Under a standard reducing-balance calculation, interest is calculated on the outstanding principal. As the principal reduces, the interest component of the payment generally falls while the principal component increases.
The Mathematical Formula Behind Bike EMI
While our EMI Calculator handles the calculation, knowing the formula helps you understand how the result is produced.
EMI = [P × r × (1+r)n] / [(1+r)n − 1]
The formula produces an estimated equated monthly payment when the loan uses the standard reducing-balance method and the interest rate remains unchanged. Actual lender calculations can differ because of their specific terms, rounding methods, fees or repayment structure.
The Amortization Schedule
One useful feature of a bike EMI calculator is an amortization schedule. It shows how each payment can be divided between interest and principal over the loan period. Early payments generally contain a larger interest component, while the principal component becomes larger as the outstanding balance decreases.

Bike Loan Calculator – EMI, Interest and Total Repayment
A bike loan calculator is useful when you want to look beyond the monthly EMI. A good calculation should help you compare three numbers:
- Monthly EMI: The estimated amount payable each month.
- Total Interest: The estimated interest paid over the full tenure.
- Total Repayment: Principal plus estimated interest over the loan period.
For example, a longer tenure can reduce the monthly EMI but may increase the total interest because the borrowed money remains outstanding for a longer period. Comparing these numbers before applying can help you choose a repayment period that fits your budget.
Key Factors: Interest Rates, Tenure and Down Payments
When you change the inputs in a bike EMI calculator, the monthly payment and total repayment can change significantly. The three main factors are the interest rate, loan tenure and down payment.
How the Interest Rate Affects Your Bike EMI
The interest rate directly affects both your monthly EMI and the total interest payable. A lower rate can reduce the cost of borrowing, while a higher rate can increase it.
- Credit profile: Your credit history and score may affect the rate a lender offers.
- Income and repayment capacity: Lenders may consider income stability and existing obligations.
- Loan and vehicle details: The lender’s product, vehicle type and other eligibility criteria can influence the loan terms.
How Loan Tenure Changes Your EMI
Tenure is a trade-off between monthly affordability and total borrowing cost. A longer tenure usually lowers the monthly EMI, but it can increase the total interest paid over the life of the loan.
| Feature | 24-Month Tenure | 60-Month Tenure |
|---|---|---|
| Monthly EMI | Usually higher | Usually lower |
| Total Interest | Usually lower | Usually higher |
| Repayment Period | Shorter | Longer |
| Overall Loan Cost | Can be lower | Can be higher |
Down Payments and On-Road Prices
The on-road price can include the ex-showroom price along with applicable registration, insurance and other charges. The exact components vary by location and purchase. Your down payment reduces the amount that needs to be financed if the lender structures the loan that way.
A higher down payment can therefore reduce the loan principal and, with the same interest rate and tenure, reduce the EMI and total interest. However, you should also keep enough cash available for your other financial needs rather than using all available savings for the down payment.
Hidden Costs: Processing Fees and Prepayment Charges
The EMI shown by a calculator is generally based on the loan amount, interest rate and tenure entered. It may not include separate processing fees, documentation charges, insurance arrangements or other lender-specific costs.
Before accepting a loan, review the lender’s Key Facts Statement and loan agreement for the applicable interest rate, fees, repayment terms and prepayment conditions. You can also review the RBI guidelines on loan transparency for relevant regulatory information.
Financial Planning and Budgeting for Your Dream Ride
A bike loan should fit comfortably within your overall monthly budget. Looking only at the EMI can be misleading because you also need to consider fuel, insurance, maintenance, registration-related costs and your existing financial commitments.
The 28/36 Rule
The 28/36 rule is a commonly discussed budgeting guideline in personal finance. It is not a universal Indian lending rule and should not be treated as a guaranteed eligibility requirement.
- The 28% figure is commonly associated with housing costs as a share of gross monthly income.
- The 36% figure is commonly associated with total debt obligations as a share of gross monthly income.
For a bike loan, the more useful approach is to calculate your expected EMI and then check whether it remains comfortable after considering your existing expenses, debts and savings goals.
Compare Your Bike Loan Before You Apply
Instead of choosing a loan based only on the advertised EMI, compare the interest rate, tenure, total interest, processing charges and other applicable costs. Two loans with similar monthly EMIs can have different total repayment amounts if their tenures or charges differ.
Strategic Budgeting With a Bike EMI Calculator
Using a bike EMI calculator is most useful when you test multiple scenarios instead of calculating only one EMI.
- Compare loan amounts: See how borrowing less changes your monthly payment.
- Compare interest rates: Check how even a small rate difference changes the total interest.
- Compare tenures: Find a balance between monthly affordability and total interest.
- Compare down payments: Check whether paying more upfront meaningfully reduces the loan cost while leaving enough emergency savings.
Impact of Down Payments on Long-Term Savings
A larger down payment reduces the amount borrowed. If the interest rate and tenure remain unchanged, a smaller principal produces a lower EMI and lower total interest.
- Lower principal: You borrow less money.
- Lower interest cost: Interest is calculated on a smaller outstanding loan amount.
- Lower EMI: With the same rate and tenure, a smaller principal generally produces a smaller monthly payment.
However, do not choose a very large down payment simply to reduce the EMI if it leaves you without sufficient savings for emergencies or other planned expenses.
Frequently Asked Questions About Bike EMI Calculators
How Accurate Is a Bike EMI Calculator?
A bike EMI calculator provides a mathematical estimate based on the loan amount, interest rate and tenure you enter. The final EMI from a lender can differ because of lender-specific calculations, rounding, fees, repayment structures or other terms.
What Is the Difference Between EMI in Advance and EMI in Arrears?
EMI in advance means an installment is collected at the beginning of the repayment arrangement. EMI in arrears generally means the installment is paid after the relevant repayment period. The exact treatment depends on the lender and loan agreement, so check the repayment schedule provided by your lender.
Does a Higher Down Payment Always Reduce the EMI?
If the interest rate and tenure remain the same, a higher down payment reduces the amount borrowed and therefore reduces the calculated EMI. It can also reduce the total interest payable because interest is calculated on a smaller principal.
What Is the Ideal Tenure for a Bike Loan?
There is no single ideal tenure for every borrower. A shorter tenure generally means a higher EMI but lower total interest, while a longer tenure generally lowers the EMI but can increase the total repayment amount. Use the calculator to compare both options against your monthly budget.
What Credit Score Is Required for a Bike Loan in India?
Lenders use their own eligibility criteria, so there is no single credit-score number that guarantees approval. Credit history, income, existing debts, repayment capacity and the lender’s policy can all affect the decision and the interest rate offered.
Can I Prepay or Foreclose My Bike Loan Early?
Many lenders provide options for part-prepayment or foreclosure, but the applicable conditions and charges depend on the loan agreement and lender. Check the applicable prepayment or foreclosure terms before making an early repayment.
How Much Down Payment Is Usually Required for a Bike Loan?
The required down payment varies by lender, vehicle, loan product and borrower profile. Rather than assuming a fixed percentage, check the lender’s current offer and calculate how different down payments affect your EMI and total interest.
Does the EMI Calculator Include Insurance and RTO Charges?
It depends on the loan amount you enter. If your financed amount is based on the on-road price, some applicable costs may already be included in that amount. If you enter only the ex-showroom price, insurance, registration and other charges may not be included. Always check the lender’s final quotation.
Can Self-Employed Individuals Get Bike Loans?
Yes, self-employed applicants can apply for bike loans, subject to the lender’s eligibility requirements. The lender may ask for income, bank, tax or business-related documents to assess repayment capacity.
Why Should I Use a Bike EMI Calculator Before Visiting a Showroom?
Using a bike EMI calculator before visiting a showroom helps you estimate your monthly payment, compare down payments and understand the total interest and repayment amount. It can also help you decide how much you are comfortable borrowing before discussing financing options.
Conclusion
A bike EMI calculator is more useful when you use it to compare complete loan scenarios rather than looking only at the monthly EMI. Loan amount, interest rate, tenure and down payment can all affect the amount you ultimately repay.
Before choosing a two-wheeler loan, compare the monthly EMI with your budget and also look at the total interest, total repayment, applicable fees and prepayment conditions. This gives you a clearer picture of the real cost of financing your bike.
At EasyInvestCalc, our goal is to make financial calculations easier to understand so you can compare different scenarios before making a financial decision.
Ready to compare your loan? Use our EMI Calculator to estimate your monthly payment and compare different loan scenarios.
Founder of EasyInvestCalc.com with 8+ years of experience in personal finance. Sunita simplifies complex financial mathematics—from SIP compounding to tax planning—empowering Indian investors to make smart, debt-free decisions based on real market mechanics.